Choosing a mutual fund should involve more than simply looking at its past returns. A good mutual fund evaluation begins by understanding whether the scheme matches your financial goals, investment horizon and risk tolerance.
Once you identify a suitable category, the next step is to understand how the fund has performed, how much risk it has taken, what it costs, and how consistently it has followed its investment strategy.
A well-rounded evaluation combines performance data with portfolio characteristics, risk measures, costs and fund-management factors. This gives investors a more informed view of whether a scheme may be suitable for their investment needs.
Key Takeaways
– Don’t judge a mutual fund solely by its historical returns.
– Compare a fund with its appropriate benchmark and category peers.
– Examine important measures such as Alpha, Beta, Sharpe Ratio and Standard Deviation.
– Consider the expense ratio, because costs can affect long-term investment outcomes.
– Review the fund’s portfolio, asset allocation, concentration and diversification.
– Consider the fund manager’s experience, investment approach and consistency.
– Use information such as the Risk-o-meter, fund factsheet, portfolio disclosures and scheme documents when evaluating a fund.
Why Mutual Fund Returns Alone Are Not Enough
Past returns tell you how much an investment has grown over a particular period. However, they don’t explain the complete journey behind those returns.
Two mutual funds can generate similar returns while taking very different levels of risk.
For example, one fund may have delivered its returns with relatively moderate fluctuations, while another may have experienced significant ups and downs. Looking only at the final return would not reveal this difference.
When evaluating a mutual fund, investors should also ask:
– How volatile has the fund been?
– Has it performed consistently across different market conditions?
– Has it beaten its relevant benchmark?
– How does it compare with similar funds?
– Is the portfolio adequately diversified?
– How concentrated is the scheme?
– What expenses are being charged?
– Has the fund remained consistent with its stated investment strategy?
Point-to-point returns can also change significantly depending on the dates selected. Therefore, looking at performance over multiple periods can provide a more meaningful perspective than relying on a single return number.
Past performance should never be treated as a guarantee of future returns.
What Should You Look at When Evaluating a Mutual Fund?
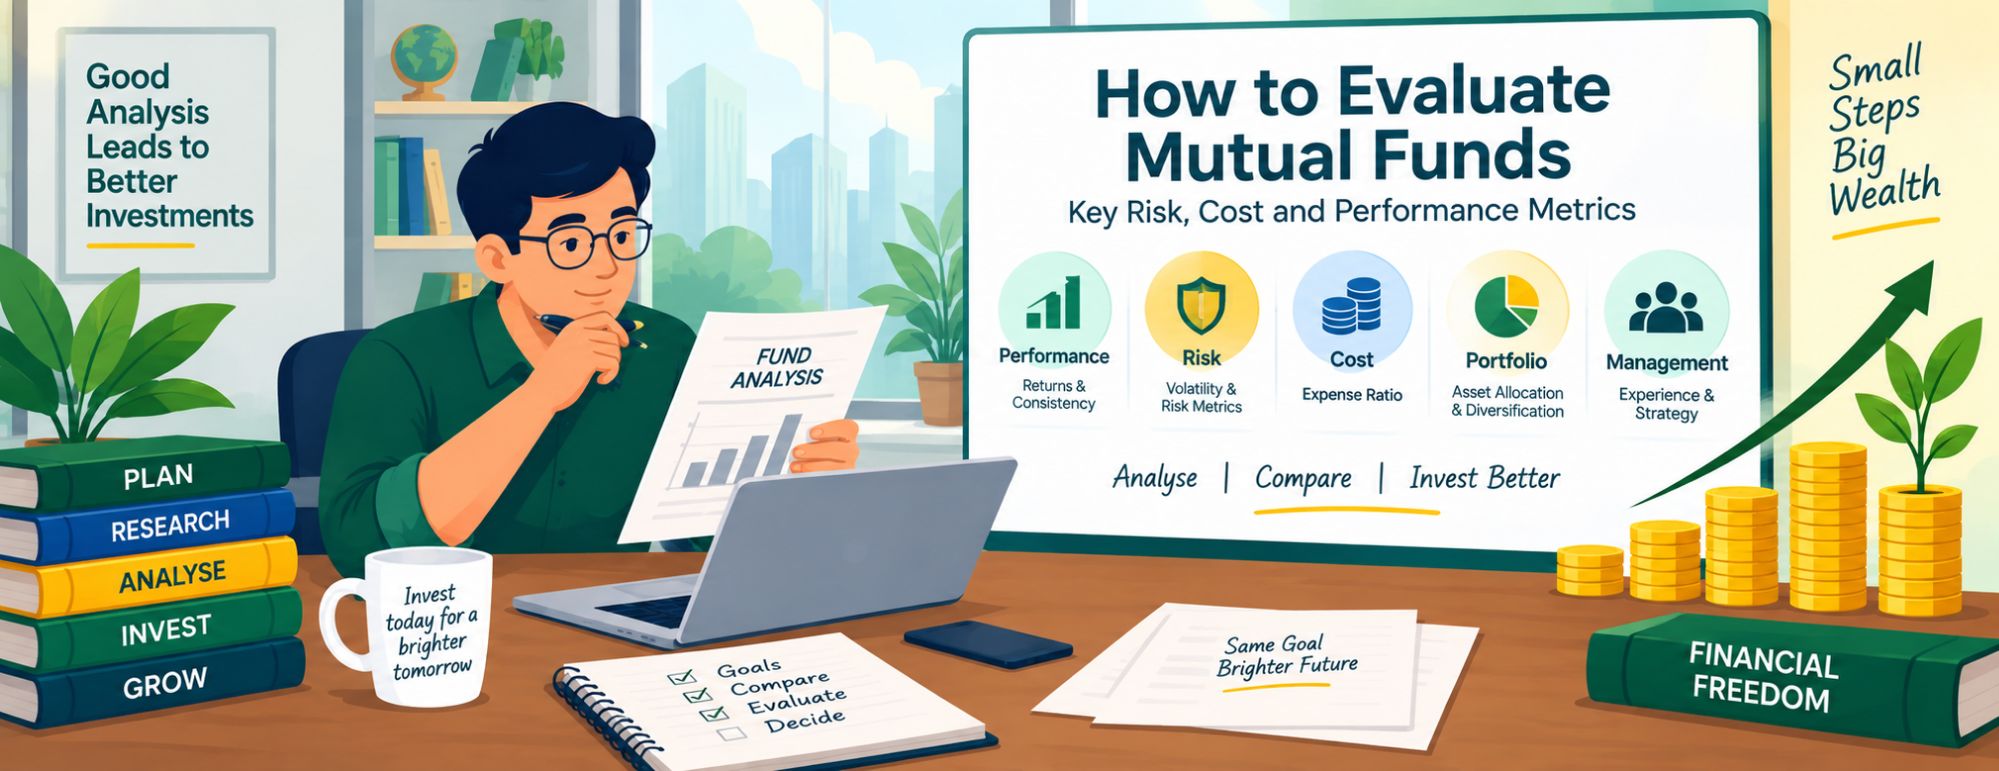
A practical mutual fund evaluation can be divided into five important areas:
1. Performance
Look at CAGR, annualised returns, rolling returns and performance relative to the benchmark.
2. Risk
Understand volatility and risk-adjusted performance using measures such as Standard Deviation, Beta, Sharpe Ratio and Alpha.
3. Cost
Check the fund’s Total Expense Ratio (TER) and understand how ongoing expenses affect returns.
4. Portfolio
Review asset allocation, sector exposure, top holdings, concentration and diversification.
5. Fund Management
Consider the fund manager’s experience, tenure, investment philosophy and consistency in managing the scheme.
No single metric should be used in isolation. The objective is to understand the complete picture.
1. Evaluate Mutual Fund Performance
Performance is one of the first things investors usually examine, but choosing the right performance measure is equally important.
CAGR
CAGR, or Compound Annual Growth Rate, represents the annualised growth rate of an investment over a period of more than one year, assuming compounding.
It can be useful when comparing long-term investment performance because it converts growth over different periods into an annualised figure.
However, CAGR does not show the fluctuations experienced during the investment period.
Annualised Returns
Annualised returns express investment performance on a yearly basis. They can help investors compare schemes with different investment periods more easily.
However, annualised returns should be considered alongside other performance measures rather than viewed independently.
Rolling Returns
Rolling returns can provide a deeper understanding of consistency.
Suppose you want to examine five-year performance. Instead of looking at only one five-year period, rolling returns examine multiple five-year periods across the fund’s history.
This can help answer an important question:
Has the fund performed reasonably well across different market periods, or was its performance dependent on a particular starting and ending date?
For long-term investors, consistency across multiple periods can be more informative than a single point-to-point return.
2. Understand Mutual Fund Risk
Returns become more meaningful when viewed alongside the risk taken to generate them.
A fund delivering high returns may not necessarily be the better choice if those returns came with significantly higher volatility than an appropriate alternative.
Here are some commonly used mutual fund risk and performance measures:
| Metric | What It Measures | What It Can Tell You |
|---|---|---|
| Alpha | Historical performance relative to a benchmark after considering market exposure | Indicates whether the fund has historically generated excess or below-expected performance relative to its benchmark |
| Beta | Sensitivity of the fund to movements in its benchmark | Shows how strongly the fund has historically moved compared with the benchmark |
| Sharpe Ratio | Return generated relative to volatility, considering the risk-free rate | Helps compare historical risk-adjusted performance |
| Standard Deviation | Variation of returns around their average | Provides an indication of historical volatility |
| Risk-o-meter | The scheme’s assessed level of risk | Helps investors understand the broad risk level of the scheme |
Alpha
Alpha is commonly used to assess a fund’s historical performance relative to its benchmark after accounting for market-related exposure.
A positive Alpha may indicate that the fund historically generated performance above the relevant benchmark expectation under the methodology used.
However, Alpha should always be considered alongside the fund’s category, benchmark, investment style and period of analysis.
Beta
Beta indicates how sensitive a fund has historically been to movements in its benchmark.
A Beta around 1 generally indicates that the fund has tended to move broadly in line with its benchmark.
A Beta above 1 indicates greater historical sensitivity, while a Beta below 1 indicates lower historical sensitivity.
Sharpe Ratio
The Sharpe Ratio is a risk-adjusted performance measure. It considers the return generated relative to the volatility taken to achieve it, after accounting for a risk-free rate.
When comparing similar mutual funds, a higher historical Sharpe Ratio may indicate better risk-adjusted performance.
It should, however, be used for appropriate peer comparisons rather than comparing unrelated categories.
Standard Deviation
Standard Deviation measures the dispersion of a fund’s returns around its average return.
In simple terms, it provides an indication of how much the fund’s returns have fluctuated historically.
A higher Standard Deviation generally indicates greater historical volatility.
3. Understand the Cost of Investing
Investment performance is not the only factor that matters. The cost of running and managing a mutual fund can also affect the investor’s overall outcome.
The Total Expense Ratio (TER) represents the recurring expenses charged to a mutual fund scheme. It is expressed as a percentage of the scheme’s assets.
Because these expenses are incurred over time, even seemingly small differences in costs can become meaningful over a long investment horizon.
For example, imagine two otherwise similar investment options delivering comparable gross returns, but one has a higher expense ratio. The higher ongoing cost can reduce the portion of returns that remains for investors.
Therefore, when comparing funds, don’t simply ask:
“Which fund has delivered higher returns?”
Also ask:
“How much did it cost to generate those returns?”
For direct and regular plans, investors should also understand the differences in expenses and distribution arrangements before choosing the appropriate option.
4. Examine the Fund’s Portfolio
A mutual fund’s portfolio shows where the scheme is actually investing its money.
Reviewing the portfolio can help investors understand whether the fund’s holdings are consistent with its investment objective.
Important areas to examine include:
Asset Allocation
Check how the fund’s assets are distributed across equities, debt, cash or other permitted investments.
Sector Allocation
For equity funds, examine whether the portfolio is heavily concentrated in particular sectors.
Top Holdings
Look at the scheme’s largest holdings. A fund with a small number of dominant positions may have greater concentration risk.
Diversification
Diversification can help reduce dependence on individual securities or sectors, although diversification does not eliminate market risk.
Portfolio Changes
It can also be useful to observe how the portfolio has evolved over time and whether the fund manager has remained consistent with the stated investment strategy.
5. Consider the Fund Manager and AMC
Numbers tell you what happened. Qualitative information can help you understand how and why it happened.
When reviewing a mutual fund, consider:
– Fund manager experience
– Tenure with the scheme
– Experience with the relevant investment category
– Investment philosophy
– Portfolio construction approach
– Consistency in following the scheme’s mandate
– How the fund has been managed during different market environments
A change in fund manager does not automatically mean that an investor should exit a scheme. Similarly, a long-tenured fund manager does not guarantee future performance.
The purpose of reviewing management information is to add context to the quantitative data.
6. Does the Fund’s AUM Matter?
AUM, or Assets Under Management, represents the value of assets managed by the mutual fund scheme.
Fund size can be relevant depending on the investment category.
For example, in mid-cap and small-cap strategies, investors may want to consider AUM along with portfolio liquidity, security concentration and the ability to buy or sell securities efficiently.
As assets grow, managing a portfolio of less-liquid securities can become more challenging.
For strategies investing primarily in large, actively traded companies, fund size may be less of a concern.
The importance of AUM therefore depends on the fund category, portfolio liquidity and investment strategy rather than simply whether the AUM is large or small.
7. Special Considerations for Index Funds
Index funds have a different objective from actively managed funds.
Instead of attempting to outperform an index through security selection, an index fund generally seeks to replicate the performance of its chosen benchmark as closely as possible.
Therefore, investors should pay particular attention to:
– Expense ratio
– Tracking error
– Tracking difference
– Benchmark selection
– Portfolio replication methodology
– Liquidity and operational efficiency
A low-cost index fund is not automatically the best choice. Investors should also consider how effectively the scheme has historically tracked its benchmark.
A Simple Framework for Evaluating a Mutual Fund
A straightforward process can make mutual fund evaluation easier.
Goal → Category → Performance → Consistency → Risk → Benchmark → Cost → Portfolio → Management
Step 1: Define Your Goal
Start by identifying why you are investing.
Your objective could be:
– Wealth creation
– Retirement planning
– Child’s education
– Buying a home
– Building an emergency reserve
– Meeting another long-term financial goal
Step 2: Select the Appropriate Category
Don’t compare every mutual fund with every other fund.
Compare funds within an appropriate category and investment objective.
A small-cap fund, a liquid fund and a large-cap fund have very different objectives and risk characteristics.
Step 3: Review Performance
Examine performance across multiple periods instead of focusing on a single return figure.
Consider CAGR, annualised returns and rolling returns where appropriate.
Step 4: Check Consistency
Look at how the fund has performed across different market environments and periods.
Consistency can provide useful context when assessing historical performance.
Step 5: Analyse Risk
Review Standard Deviation, Beta, Sharpe Ratio, Alpha and the Risk-o-meter.
The objective is to understand the level and nature of risk associated with the historical returns.
Step 6: Compare With the Right Benchmark
A fund should be evaluated against its relevant benchmark, not simply against the overall stock market or another unrelated fund.
Also consider how it compares with suitable category peers.
Step 7: Review Costs
Check the Total Expense Ratio and understand the cost structure of the plan you are considering.
Step 8: Examine the Portfolio
Review asset allocation, sector exposure, top holdings, concentration and diversification.
Step 9: Understand the Management Approach
Finally, consider the fund manager, investment philosophy and whether the scheme has maintained consistency with its stated mandate.
Final Thoughts
Evaluating a mutual fund is not about finding the fund with the highest historical return.
A better approach is to understand the relationship between return, risk, cost, portfolio construction and consistency.
A fund that has delivered strong returns may still be unsuitable if its risk level does not match your investment horizon or tolerance for volatility. Likewise, a lower-cost fund may not necessarily be appropriate if its investment objective does not match your financial goal.
The most important question is therefore not:
“Which mutual fund has the highest return?”
Instead, ask:
“Does this mutual fund’s objective, risk, cost, portfolio and historical behaviour fit my investment needs?”
Using a structured evaluation process can help investors make more informed decisions and avoid choosing a mutual fund based on a single performance number.
Leave a Reply