Generate Regular Income from Your Mutual Fund Investments
From Mutual Fund Corpus to Regular Income: Understanding SWPs
Summary: Retirement should be about enjoying the financial security you have built—not constantly worrying about how to turn your savings into income. A Systematic Withdrawal Plan (SWP) can help convert a mutual fund corpus into a regular cash flow while keeping the remaining investment in the market.
Building a substantial mutual fund corpus is only one part of financial planning. The next question is often more important:
How can you use that corpus to meet your regular expenses without withdrawing everything at once?
This is where a Systematic Withdrawal Plan (SWP) can be useful.
An SWP allows you to withdraw a predetermined amount from a mutual fund at regular intervals, such as monthly, quarterly or annually. It can be particularly useful during retirement or whenever an investor needs a regular income from an accumulated investment corpus.
How Does an SWP Work?
Setting up an SWP is relatively straightforward.
You instruct the mutual fund to redeem a specified amount from your investment at a chosen frequency.
For example, suppose you have a ₹50 lakh mutual fund corpus and set up a monthly SWP of ₹25,000.
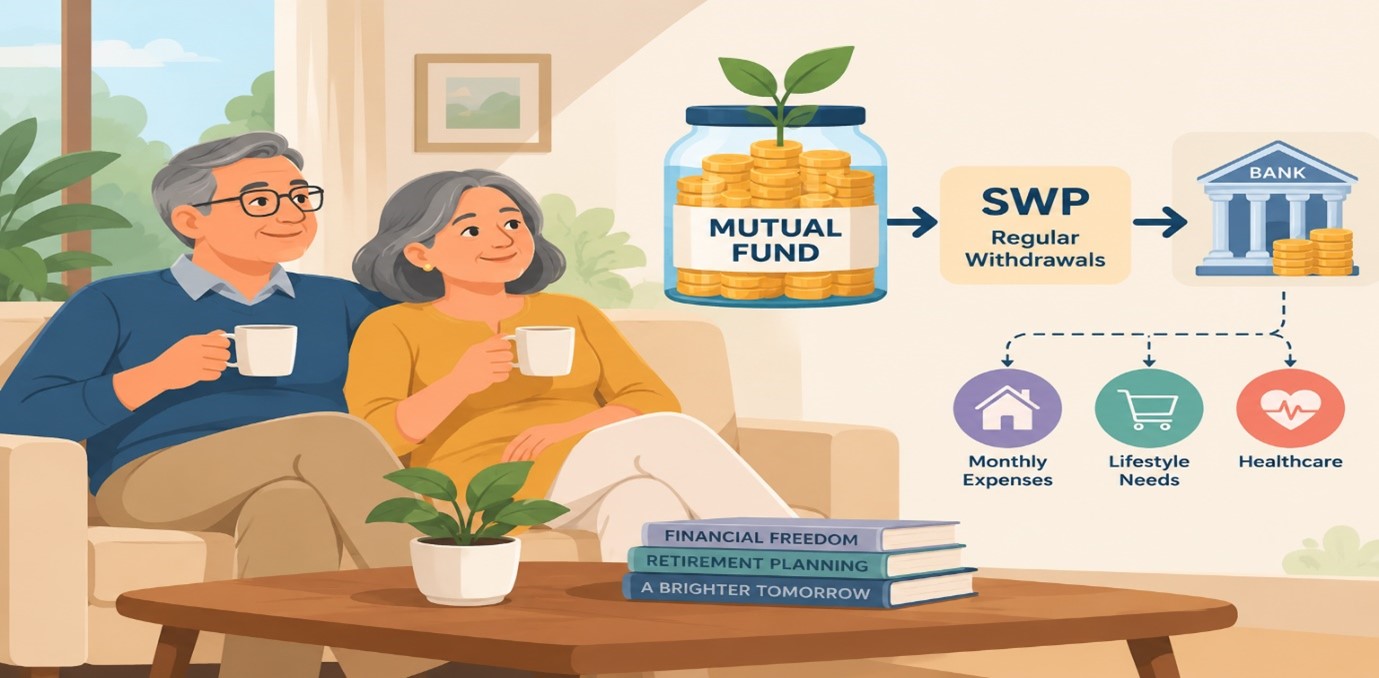
Each month, mutual fund units worth ₹25,000 are redeemed and the proceeds are transferred to your bank account. The units that are not redeemed remain invested.
The important point is that an SWP does not mean withdrawing a fixed number of units. Instead, a specified amount is withdrawn, so the number of units redeemed can vary depending on the fund’s NAV at the time of withdrawal.
The remaining corpus continues to participate in market movements.
However, an SWP does not guarantee that the corpus will continue growing. The sustainability of withdrawals depends on factors such as the withdrawal rate, investment returns, market conditions and the length of the withdrawal period.
How Are SWP Withdrawals Taxed?
An SWP withdrawal is treated as a redemption of mutual fund units. Therefore, taxation applies to the capital gains component of the redemption rather than simply treating the entire withdrawal as income.
The applicable tax depends on the type of mutual fund, the holding period and prevailing tax rules.
For example, equity-oriented mutual funds may attract different short-term and long-term capital gains tax rates depending on the holding period. Tax rules for debt-oriented funds can also differ.
Therefore, investors should consider the tax implications when deciding how much to withdraw and how frequently to withdraw it.
Tax rules can change, so the applicable rates and treatment should always be checked for the relevant financial year.
How Much Should You Withdraw?
There is no universal SWP withdrawal rate that is suitable for every investor.
A commonly discussed range is around 4%–6% of the initial corpus per year, but this should be treated only as a general planning reference—not a guaranteed safe withdrawal rate.
For example, with a ₹1 crore corpus, a 4% annual withdrawal would be ₹4 lakh, or approximately ₹33,333 per month. At 6%, the annual withdrawal would be ₹6 lakh, or approximately ₹50,000 per month.
But whether such a withdrawal is sustainable depends on several factors:
- Investment time horizon
- Expected portfolio returns
- Market volatility
- Asset allocation
- Inflation
- Withdrawal amount
- Sequence of market returns
- Other sources of income
- Changes in spending requirements
A higher withdrawal rate can put greater pressure on the corpus, particularly when markets experience significant declines early in the withdrawal period.
SWP vs IDCW: What’s the Difference?
Investors sometimes compare SWPs with IDCW (Income Distribution cum Capital Withdrawal) options.
They work differently.
An IDCW payout is declared by the mutual fund according to the scheme’s provisions and available distributable surplus. The amount and timing are therefore not the same as receiving a fixed, investor-controlled withdrawal.
With an SWP, the investor specifies the amount and frequency of withdrawals, subject to the scheme’s applicable terms.
This provides greater control over cash-flow planning.
Tax treatment can also differ depending on the nature of the payout and the type of mutual fund. Therefore, investors should compare the applicable tax consequences rather than assuming that one option is automatically more tax-efficient.
Why SWP Can Be Useful in Retirement
For retirees, one of the biggest challenges is converting accumulated wealth into a predictable cash-flow structure.
An SWP can help create a regular withdrawal schedule while allowing the remaining corpus to stay invested.
For example, an investor might use:
Mutual fund corpus → SWP → Monthly bank credit → Regular expenses
This can provide a systematic approach to accessing investments rather than making large, irregular withdrawals whenever money is required.
However, the portfolio still remains exposed to market risk. An SWP should therefore be designed alongside an appropriate asset allocation and cash-flow plan, rather than viewed as a guaranteed pension.
The Bottom Line
An SWP can be a practical way to convert a mutual fund corpus into regular cash flow while retaining control over the withdrawal amount and frequency.
But the objective should not simply be to withdraw as much as possible.
A sustainable withdrawal strategy needs to consider your financial goals, investment horizon, spending requirements, asset allocation, market risk, inflation and taxation.
The real benefit of an SWP is not just receiving money every month. It is creating a structured way to use the wealth you have accumulated while giving the remaining corpus an opportunity to continue working toward your longer-term financial needs.
Leave a Reply